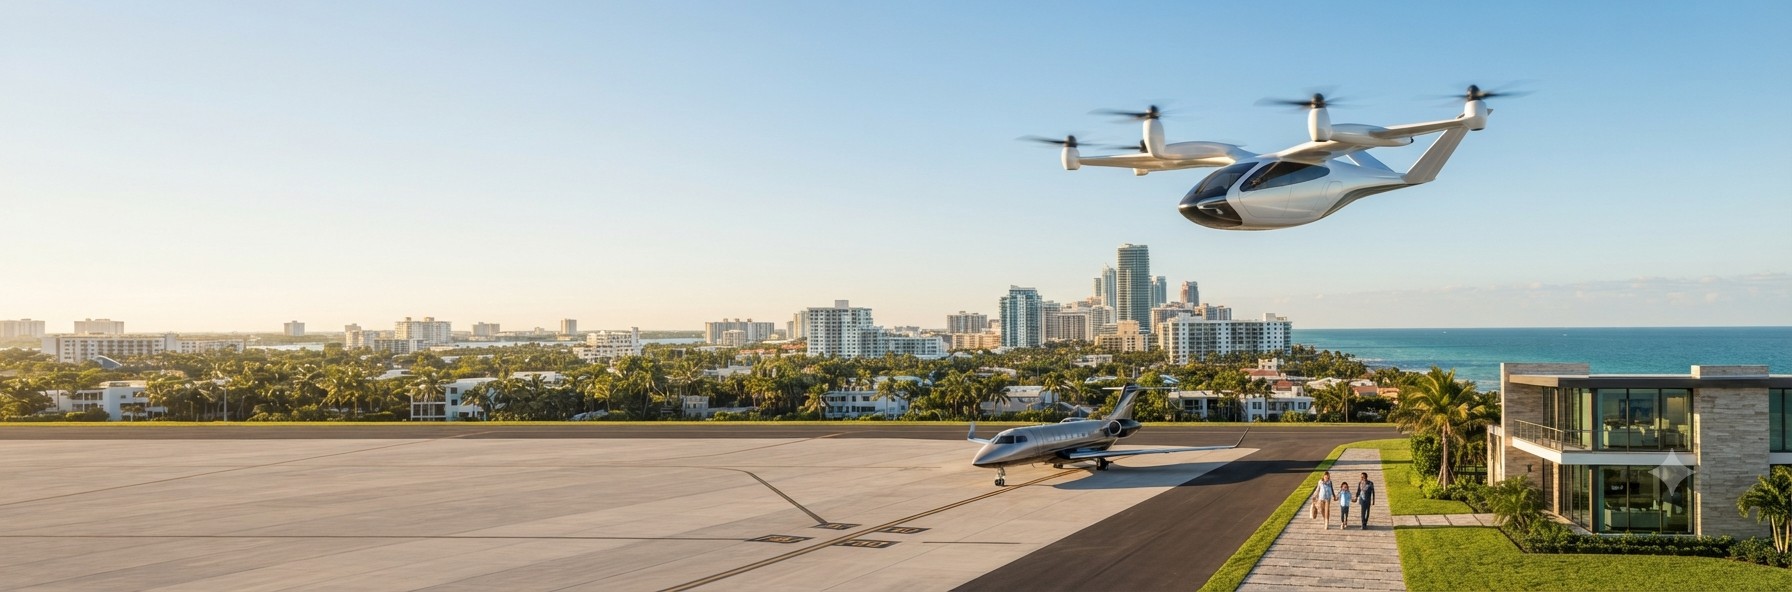
Intelligence Brief · Global Lifestyle OS · July 2026
China is building a trillion-dollar fleet of aircraft, drones, and autonomous vehicles. Global Lifestyle OS already owns the eight-layer household relationship every one of those vehicles is trying to reach.
China's Civil Aviation Administration projects the country's low-altitude economy will reach RMB 1.5 trillion in 2025 and RMB 3.5 trillion by 2035, now an independent strategic priority in the 15th Five-Year Plan. At the same moment, Europe's two best-funded eVTOL manufacturers — Lilium and Volocopter — collapsed within three months of each other, together with an estimated €3 billion in prototype capital that never carried a paying passenger. Above the Machine documents why this is structurally predictable for a vehicle-only business model, and why Global Lifestyle OS's eight-layer household relationship — mobility being only one part of it — is insulated from the same risk, at any point in the low-altitude economy's boom-bust financing cycle.
13 Chapters
RMB 3.5T by 2035
€3B Burned on Prototypes (Europe)
Eight-Layer Household Model
⊘ Not for Public Distribution
RMB 3.5T
China's Low-Altitude Economy Projection by 2035 (CAAC)
€1.5B
Lilium's Burn Before Liquidation, 2025
−99.5%
Volocopter's Sale Price vs. 2022 Peak Valuation
2028
Korea's K-UAM Demonstration Target — Still Contingent
Document Contents
A trillion-dollar policy tailwind and a capital graveyard are the same story — a hardware bet with no mechanism to monetise the client once the trip ends.
China's low-altitude economy is real, state-backed, and growing fast. It is also, so far, a vehicle-manufacturing and airspace-operations bet — and the eighteen months that produced its most aggressive policy targets also produced the collapse of Europe's two best-funded eVTOL manufacturers. That is not a coincidence. It is the structural ceiling of a business model that only monetises the moment a client is inside the vehicle.
Above the Machine applies the eight-layer household model this series has already documented for GLO's core client base to a new comparison: not against another lifestyle platform, but against an entire government-anchored industrial category building the vehicles GLO's members will eventually ride in.
- The Low-Altitude Economy — Trillion-dollar policy momentum, provincial funding races, and a certification lead China holds well ahead of Western timelines
- Korea's Version — K-UAM's own 2028 target, a stalled capital-region rollout, and a July 2026 public flight failure that shows why owning the vehicle is not the same as owning the client
- The Capital Graveyard — Lilium and Volocopter's collapse within three months of each other, and why certification timelines make a pure hardware bet structurally fragile
- The Structural Flaw — A vehicle company monetises exactly one trip. GLO's members do not stop being members when they land
- What GLO Actually Sells — Eight integrated layers — mobility, education, medical, property, security, logistics, community, and AI household operations
- Same Technology, Different Business Model — GLO's staged, demand-gated eVTOL approach versus the speculative capital bet that ended Lilium and Volocopter
- The Asymmetry & Realism — Why certified survivors like EHang, Joby, and Archer need GLO's pre-qualified household base more than GLO needs any single manufacturer, and an honest account of what operates today versus what is roadmap
01 · The Paradox
Record policy backing, record capital destruction
China's low-altitude economy carries trillion-dollar state backing and a first-mover certification lead — while, in the same window, an estimated €3 billion in European eVTOL prototype capital never carried a paying passenger.
02 · The Structural Flaw
One vehicle, one trip, one relationship that ends
Every company in this category — survivors and casualties alike — monetises the same underlying unit: a seat on a single flight. When the trip ends, so does the revenue relationship, until the next one is booked.
03 · The Model
Priced per household, not per seat
GLO's members do not stop being members when they land. The same relationship that arranged their flight also arranges their child's school, their family's medical coverage, and their next residence.
The vehicle is one touchpoint inside a relationship that runs twelve months a year.
"Global Lifestyle OS's members do not stop being GLO members when they land. The vehicle is one touchpoint inside a relationship that runs twelve months a year, not a transaction that ends when the door opens."
Eight Layers, Not One Vehicle
The same platform documented across this series — compared directly against a vehicle-only business model.
Each layer below is documented in its own brief in this series, with an honest separation of what operates today and what is staged roadmap (Chapter 12 of the full brief).
| Dimension | A vehicle-only low-altitude economy company | The Global Lifestyle OS application |
|---|
| Revenue model | Per seat, per trip — priced against a certified, depreciating asset on a commoditising cost-per-mile basis | Per household, per year, across eight layers: mobility, education, medical, property, security, logistics, community, AI operations |
| Capital risk | Full certification and manufacturing risk carried directly — the exposure that ended Lilium and Volocopter | Staged, demand-gated integration; aircraft purchased only for certified routes with validated demand |
| Client relationship | Ends when the flight ends; resumes only when the next trip is booked | Continuous, twelve months a year, unrelated to which mobility layer a family used to arrive |
| Cross-sell | One: another flight | Seven other active household relationships — none reachable by any single-layer mobility provider |
The full brief details each layer's current operating status, the pilot history behind the household model, and the honest limits of what is not yet built.
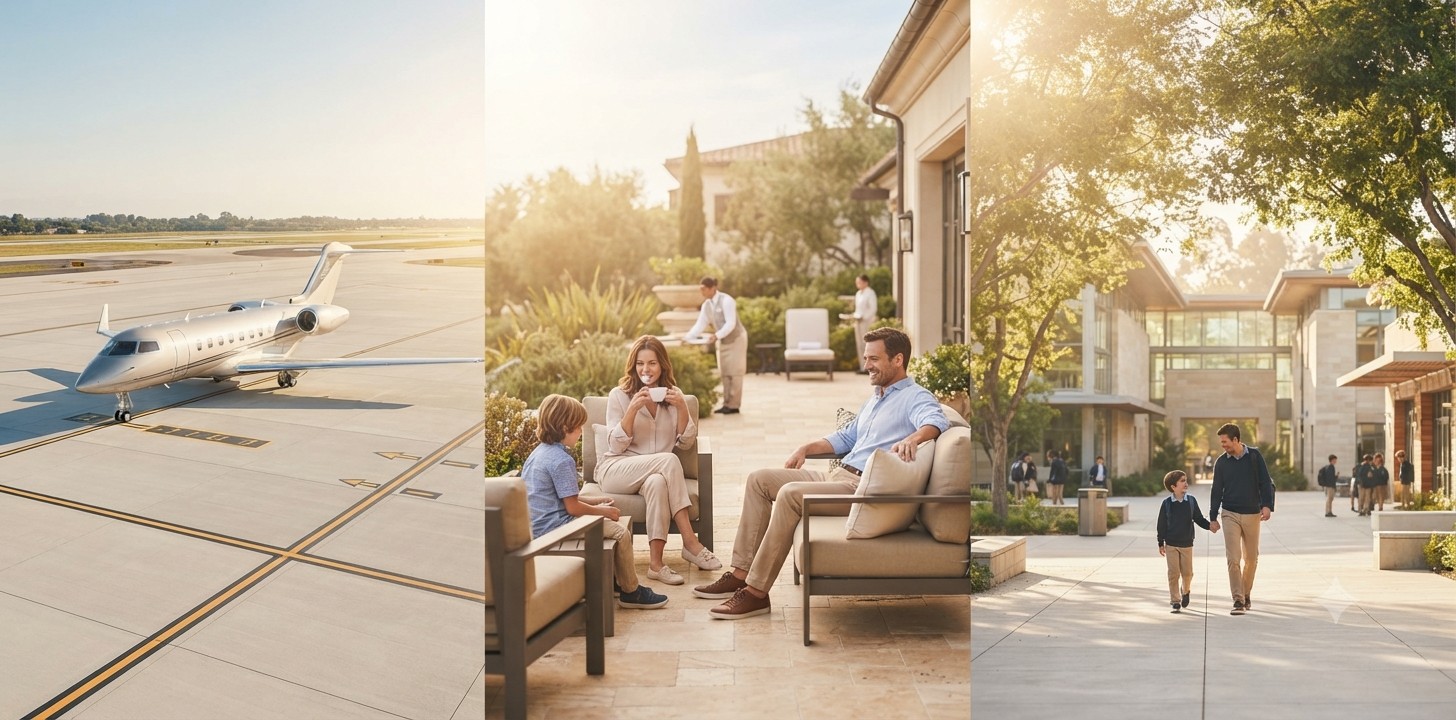
One household, one continuous day — mobility, residence, and education as a single relationship.
Competitive Landscape
Every player in this ecosystem holds one fragment. None holds the combination.
A certified eVTOL or electric-yacht manufacturer can build and operate the vehicle — but has no education platform, no medical retainer, no property coordination, and no mechanism to monetise a client relationship once the trip ends. A luxury concierge or charter broker can arrange access to multiple mobility types — but coordinates each booking individually rather than integrating them into one household relationship. A government-backed regional programme, including Korea's own K-UAM initiative, can build regulatory and physical infrastructure — but is years from commercial service and has no client-facing business model at all.
Global Lifestyle OS already operates the aviation and AEV layers this brief depends on, five years live, and is positioned to integrate eVTOL and electric-marine technology on its own staged, demand-validated timeline as the manufacturers documented in this brief's survivor column mature their offerings — without having carried any of the capital risk that destroyed Lilium and Volocopter.
"The machine changes every product cycle. The relationship above it does not."
Access Policy
Why this document is not publicly available
Above the Machine names the specific market data behind China's low-altitude economy, the capital-graveyard mechanics behind Lilium and Volocopter's collapse, GLO's staged eVTOL integration approach, and the partnership landscape — alongside an honest treatment of what operates today versus what is roadmap.
Releasing this analysis publicly would hand competitors and manufacturers the exact market read and business-model reasoning behind GLO's structural position in this category. It is appropriate for a partner, investor, or manufacturer evaluating a strategic relationship, and inappropriate for general distribution.
Why Access Is Controlled
This is the market thesis and business model behind a new client category.
Not low-altitude economy news.
The brief names the data, the layer-by-layer comparison, GLO's capital deployment approach, and the go-to-market reasoning with enough precision to be actionable for a partner and instructive for a competitor. We apply the standard any serious organisation applies to its most commercially sensitive strategic analysis.
Access Criteria
Who this document is for
✓
Eligible — eVTOL, AEV & Electric-Marine Manufacturers
Certified or near-certified vehicle manufacturers and their partnership teams
Organisations evaluating a channel or integration partnership that provides instant access to a pre-qualified, repeat, high-frequency client base without the years and capital typically required to build one independently.
✓
Eligible — Investors & Family Offices
Institutional and private investors evaluating the low-altitude economy
Investors assessing GLO's structural position relative to vehicle-only manufacturers, and family offices or advisors evaluating GLO itself as a lower-risk way to gain exposure to this category.
✗
Not Eligible
All other parties
Competitors or their representatives. Researchers without a specific verifiable decision context. Individuals who cannot clearly identify a decision they are authorised to make that this document would directly inform.
✗
Wrong Fit
General press and speculative research inquiries
This brief is B2B infrastructure and market-structure analysis. It contains no investment advice and no claims of signed manufacturer agreements beyond what is documented as roadmap. Media inquiries should use the public contact channels instead.
Confidential Access Request
Request access to the Intelligence Brief
All requests are reviewed personally by the GLO founder. If this is relevant to a decision you are authorised to make, send your request directly.